Banking & Finance

Banking & Finance

  • Kenya Tax Guide for Foreign Investors: 2026 Setup Checklist

    Kenya Tax Guide for Foreign Investors: 2026 Setup Checklist


    Kenya Tax Guide for Foreign Investors: 2026 Setup Checklist

    Foreign investment in Kenya does not become a tax problem when the first annual return is due. It becomes a tax problem when the business model, contracts, payroll, invoicing and funding arrangements are set up without a common plan.

    This Kenya tax guide for foreign investors sets out the decisions to make before you incorporate, hire, import, invoice or pay a parent company. It is written for an international business establishing operations in Kenya, rather than a passive investor buying a listed security.

    Short answer: a Kenyan subsidiary is generally taxed at 30% and a non-resident company at 37.5% on Kenya-derived income. VAT is generally 16%, VAT registration is required at KES 5 million of annual taxable turnover, and corporate income tax returns are due by the end of the sixth month after the accounting period. Those headline figures matter, but the larger risk often sits in payroll, cross-border payments, related-party charges and the records supporting them. KRA’s corporate-tax guidance and company filing guidance confirm the current corporate rates and return timetable.

    Who this guide is for: foreign groups setting up a Kenyan subsidiary or branch, businesses entering Kenya through a distributor or digital platform, and investors planning a Kenyan acquisition, operating company or exit.
    Kenya tax guide for foreign investors, showing a red thread moving through a paper Kenya outline

    Start with the operating model, not the tax rate

    The right structure depends on what the Kenyan business will actually do. Who signs contracts? Where are employees based? Who owns the customer relationship, intellectual property and stock? How will the Kenyan business be funded? Where will services be performed?

    Those facts determine the tax analysis. A label such as “representative office” does not by itself prevent a Kenyan taxable presence if the activity on the ground is commercial.

    Operating modelCore tax questionWhat to settle before launch
    Kenyan subsidiaryWill the Kenyan company have the people, contracts and records needed to earn its margin?Funding, intercompany services, VAT position, payroll and dividend path.
    Kenyan branch or other permanent establishmentIs the non-resident carrying on business through a Kenyan taxable presence?Profit attribution, registrations, local compliance and remittance model.
    Distributor or agent modelIs the local party an independent distributor or creating a Kenyan taxable presence for the foreign principal?Contract authority, pricing, stock, customer terms and tax obligations.
    Digital or marketplace modelDo Kenyan users, VAT rules or significant-economic-presence rules create a Kenyan tax obligation?User location, service flow, platform role, registration and invoicing.

    Do not choose a subsidiary simply because a branch has a higher headline rate. The answer can turn on commercial liability, regulatory licences, financing, profit repatriation, permanent-establishment risk and the group’s future exit plan. Build the legal and tax model together.

    Kenya tax guide for foreign investors: key taxes at a glance

    Tax or obligationCurrent starting pointWhy it matters to an investor
    Corporate income tax30% for resident companies; 37.5% for non-resident companiesThe entity and taxable-presence analysis should be fixed before the first contract is signed.
    VAT16% general rateApplies to taxable supplies and imports. A VAT-registered business needs an invoice and input-tax process that works from day one.
    VAT registrationKES 5 million annual taxable turnover, with voluntary registration available in some casesRegistration may be required before the business reaches the threshold if it expects to do so.
    PAYEProgressive individual rates from 10% to 35%Employer registration, payroll configuration and benefits treatment need to be ready before the first salary run.
    Withholding taxDepends on payment type and recipient statusParent-company charges, interest, royalties and service fees should be reviewed before payment.
    Capital gains tax15% of net gain, generally a final taxThe exit route should be considered at acquisition and shareholder-agreement stage, not only on sale.

    Kenya also offers incentive regimes for qualifying operations. A Special Economic Zone enterprise, developer or operator may qualify for corporation tax at 10% for the first 10 years and 15% for the next 10 years. Certain Export Processing Zone enterprises can receive a 10-year corporate-tax holiday followed by a 25% rate for the next 10 years. These are eligibility-based regimes, not default outcomes. KRA’s investment-incentives guidance should be checked against the intended activity and licensing position before the investment model assumes a reduced rate.

    A note on small-business regimes and global minimum tax

    Turnover tax is not usually the right regime for an international operating company. KRA states that it is charged at 1.5% of gross sales for eligible resident businesses with turnover from KES 1 million to KES 50 million, and it does not apply to non-resident taxpayers. It also does not fit every type of income. KRA’s turnover-tax guidance is a useful starting point.

    At the other end of the scale, a very large multinational group should separately assess Kenya’s minimum top-up tax framework and its group-wide reporting requirements. An incentive or a low effective tax rate in one entity should not be assumed to settle the group-level analysis. The current Income Tax Act is the starting point, but this is an area for a tailored calculation.

    VAT, eTIMS and imported services: design the invoicing process early

    VAT is commonly where a new entrant discovers that an accounting issue is actually a tax-control issue.

    The general VAT rate is 16%. A business that supplies or expects to supply taxable goods and services worth KES 5 million or more in a year must register. A business below the threshold may be permitted to register voluntarily. VAT returns and payment are due by the 20th day of the following month. KRA’s VAT guidance also confirms that VAT-registered taxpayers must onboard eTIMS.

    For a foreign investor, the practical questions are more important than the rate:

    1. Is each supply taxable, zero-rated or exempt?
    2. Can the business issue compliant eTIMS invoices from the first commercial transaction?
    3. Are supplier invoices and purchase records sufficient to support input-VAT recovery?
    4. Is there VAT on a service purchased from a non-resident supplier?
    5. Does the business make digital supplies into Kenya that require non-resident VAT registration regardless of the KES 5 million threshold?

    Reverse VAT on services imported into Kenya

    Imported services can trigger reverse VAT. KRA states that any importer of an imported service is liable to pay it, irrespective of VAT-registration status, where the service is provided by a non-resident who is not required to register for Kenyan VAT. The tax point is the earliest of receiving the service, receiving the invoice or making payment. Tax paid for use in a registered person’s taxable business may be deductible as input tax in a later VAT return. See KRA’s explanation of VAT on imported services.

    This is why a software subscription, group-management charge, licence fee or overseas consultancy agreement should be reviewed before the first invoice is paid.

    Payroll in Kenya: build the full statutory stack into the first salary run

    Payroll should not be treated as a routine HR task. It is a monthly tax and statutory-compliance process.

    KRA requires an employer to deduct PAYE from employment income and remit both the tax and the PAYE return by the ninth day of the following month. The current PAYE bands range from 10% to 35%; personal relief is available to resident individuals, subject to the applicable rules. KRA’s PAYE guidance should be used to configure the first payroll and employee-benefit treatment.

    The payroll stack normally requires the following additional checks:

    ItemCurrent position to confirm in payroll setup
    Social Health Insurance FundThe regulations provide for a 2.75% monthly contribution based on gross salary or wage, subject to a KES 300 minimum. The employer needs to ensure the deduction and remittance process is configured correctly. Social Health Insurance Regulations
    Affordable Housing Levy1.5% of the employee’s gross monthly salary is deducted from the employee, and the employer contributes a matching 1.5%. KRA states that remittance is due by the ninth working day after month-end. KRA notice
    NSSFContributions sit within a phased statutory regime. Use the current annual NSSF employer notice and earning limits, rather than an old payroll template. NSSF employer notice
    NITA industrial training levyNITA states that employers should pay KES 50 per employee per month. It is an employer levy, not an employee payroll deduction. NITA guidance

    For expatriate staff, add a separate workstream for immigration status, Kenyan tax residence, employment-contract wording, benefits, tax equalisation and treaty analysis. Do not assume a foreign payroll arrangement eliminates Kenyan employment-tax exposure where services are performed in Kenya.

    Withholding tax: review every payment leaving Kenya before it is made

    Withholding tax is often the first cross-border tax cost a new Kenyan business sees. The payer must identify the payment type, the recipient’s tax status, the domestic rate, whether a treaty can reduce the rate, and the evidence needed to support the position.

    For common payments from a Kenyan company to a non-resident, KRA’s published domestic rates include:

    Payment to a non-residentStandard domestic withholding-tax rate
    Dividend15%
    Interest15%
    Royalty20%
    Management, professional or training fee20%
    Contractual payment, including certain construction or supply payments20%

    These are starting points, not a substitute for classifying the payment. Kenya’s rules vary by payment type and can include special treatment for instruments, recipients and regimes. KRA’s withholding-tax guidance should be read with the contract before payment.

    A valid double-tax agreement may reduce a non-resident rate, but treaty relief should not be assumed merely because the parent company is established in a treaty country. Confirm the recipient’s tax residence, beneficial ownership where relevant, the treaty article, the Kenyan documentation and the payment’s real character.

    Timing matters: KRA requires withholding tax to be remitted within five working days of deduction. For a non-resident with no permanent establishment in Kenya, the tax withheld is generally final tax. KRA’s withholding-tax FAQ sets out the current operational position.

    Related-party transactions: localise the transfer-pricing file before an audit does it for you

    Related-party transactions are not a year-end clean-up exercise. They should be documented when the group decides the price, service scope, financing terms or intellectual-property arrangement.

    The common risk areas are:

    • management and shared-service charges;
    • shareholder or intercompany loans;
    • royalties and software or intellectual-property licences;
    • supply-chain pricing;
    • guarantees; and
    • dealings between a non-resident and its Kenyan permanent establishment.

    Kenya’s transfer-pricing framework is grounded in section 18(3) of the Income Tax Act and the transfer-pricing rules. KRA describes the rules as heavily informed by OECD transfer-pricing guidelines. KRA’s transfer-pricing overview is a helpful introduction, but the group should maintain fact-specific evidence that its Kenyan terms are arm’s length.

    Groups should also assess country-by-country reporting, master-file and local-file obligations. The Income Tax Act uses KES 95 billion of consolidated group turnover as the current threshold for the country-by-country reporting provisions. See the current Income Tax Act.

    Digital businesses: significant economic presence tax and VAT can both apply

    A foreign business does not need a traditional office to trigger Kenyan tax questions.

    Significant economic presence tax, or SEPT, applies to a non-resident whose income from providing services accrues in or is derived from Kenya through a business carried out over a digital marketplace, where the user is located in Kenya. The current statutory framework excludes, among others, a non-resident offering the services through a Kenyan permanent establishment and a non-resident with annual turnover below KES 5 million. Taxable profit is deemed to be 10% of gross turnover and the rate is 30% of that deemed profit, which produces an effective 3% charge on gross turnover under the current formula. Section 12E of the Income Tax Act is the primary source.

    SEPT is separate from VAT. KRA says non-resident persons making supplies into Kenya over the internet, an electronic network or a digital marketplace must register for VAT whether or not they meet the KES 5 million VAT threshold. Map both obligations before pricing a Kenyan digital offer. KRA VAT guidance

    Imports and exits need a tax plan too

    If you import goods or equipment

    Tax and customs planning should be part of the procurement process, not a post-arrival reconciliation. Under the Finance Act 2026, KRA says that from 1 September 2026 importers must obtain and retain an export declaration, export entry, customs export certificate or equivalent document from the country of export. The record should support the importer, exporter, goods, quantity, value, tariff classification and country of export. KRA’s Finance Act 2026 guidance explains the operational change.

    If you expect to exit through a share sale

    Capital gains tax is currently charged at 15% of the net gain and is a final tax. KRA also identifies situations in which gains from indirect interests can be caught, including certain transfers involving non-residents and Kenyan shares or Kenyan immovable property. KRA’s capital-gains-tax guidance should be reviewed before signing the sale documents, not after completion.

    An investor should therefore decide early whether a future sale is more likely to be an asset sale, a sale of Kenyan shares or a sale higher up the group. The tax result can differ materially.

    A 90-day tax launch plan for a Kenyan operation

    This is the practical asset in this guide. Use it to sequence the work before the operation becomes difficult to unwind.

    Days 1 to 30: define the tax footprint

    1. Confirm the legal structure and who will sign Kenyan customer and supplier contracts.
    2. Map money flows: customer revenue, employee costs, imports, debt, dividends, management charges, royalties and service fees.
    3. Obtain the required KRA PINs and register the right tax obligations.
    4. Test VAT status, eTIMS onboarding and the first invoice flow.
    5. Identify any licence, SEZ, EPZ, customs or investment-certificate question before commercial activity begins.

    Days 31 to 60: make the recurring processes work

    1. Configure PAYE, Social Health Insurance Fund, Affordable Housing Levy, NSSF and NITA processes before the first salary run.
    2. Put related-party agreements in place and document the pricing method, deliverables and approvals.
    3. Create a withholding-tax review gate for every payment to a non-resident or related party.
    4. Set procurement rules for imported services, imported goods, eTIMS invoices and VAT-supporting records.

    Days 61 to 90: make the position defensible

    1. Build a monthly compliance calendar with named owners and backups.
    2. Reconcile tax returns to the general ledger, payroll and invoicing records.
    3. Create an evidence folder for key tax positions, treaty documents, invoices, contracts and transfer-pricing support.
    4. Review the exit route, shareholder documents and group funding before additional capital is injected.

    Kenya tax compliance calendar: the deadlines to put in your launch plan

    ObligationGeneral timing
    PAYE return and paymentBy the 9th day of the following month
    Affordable Housing LevyBy the 9th working day after month-end
    Social Health Insurance Fund contributionThe regulations specify the 9th day of the month for salaried households
    Withholding taxWithin 5 working days after deduction
    VAT return and paymentBy the 20th day of the following month
    Company income-tax returnBy the end of the sixth month after the accounting period ends

    Build the calendar around the company’s actual accounting period, contracts and payroll date. It is safer to create a single controlled calendar than to leave tax, finance, HR and procurement each managing one part of the same obligation.

    Frequently asked questions

    Does every foreign investor need a Kenyan company?

    No. The appropriate model depends on the activity, contracts, people, tax presence, regulatory position and funding structure. A subsidiary, branch, distributor, agent or digital model can each have different tax effects.

    When must a foreign business register for Kenyan VAT?

    The general VAT threshold is KES 5 million of annual taxable turnover. However, non-resident persons making supplies into Kenya over the internet, electronic network or digital marketplace have a separate VAT-registration rule. Check the model before the first supply.

    Can a Kenyan subsidiary pay management fees or royalties to its parent company?

    It can, but the payment must be correctly characterised, supported by a real service or licence arrangement, priced on arm’s-length terms and reviewed for withholding tax, VAT and treaty consequences before payment.

    Does a tax treaty automatically reduce withholding tax?

    No. Treaty relief is fact-specific. The recipient’s residence, the payment type, treaty wording, supporting documentation and any procedural requirements should be confirmed before the payment is made.

    What is the most common tax-control failure in a new Kenyan operation?

    Treating tax as a return-filing exercise. The exposure commonly begins earlier, in a contract, a payroll configuration, an overseas invoice, a missing eTIMS record or an unsupported related-party charge.

    Get the structure right before the first payment leaves Kenya

    MN Legal helps foreign investors align incorporation, contracts, tax registration, payroll setup, regulatory compliance and cross-border arrangements before they become expensive to unwind. Explore MN Legal’s practice areas or contact the firm to discuss a fact-specific market-entry plan.


    This article is for general information only and is not legal or tax advice. Kenyan tax law, KRA practice, exchange-rate effects and filing requirements can change. Obtain advice on your facts before acting. Last reviewed 3 September 2026.
  • Finance Bill 2026: KRA’s New Data Powers and What Founders Must Know    |    MNL Advocates LLP

    Finance Bill 2026: KRA’s New Data Powers and What Founders Must Know | MNL Advocates LLP

    When the Taxman Becomes the Data Collector: KRA’s New Powers Under Finance Bill 2026 and What Founders Must Know

    Quick Summary: The Finance Bill 2026, published on 5 May 2026 and tabled before the National Assembly, proposes a new Section 18A into the Tax Procedures Act. The provision empowers the Kenya Revenue Authority Commissioner to issue tax assessments using secondary data including eTIMS records, withholding tax declarations, and whistleblower reports. This creates a direct collision with the Data Protection Act 2019 and raises constitutional questions under Articles 24, 27, 31, and 47 of the Constitution of Kenya. Founders and business operators need to act now.

    Every year, Kenya’s Finance Bill arrives with new proposals. Every year, businesses brace. Most founders read the headline changes, note the new rates, and move on. Finance Bill 2026, published on 5 May 2026 and formally tabled before the National Assembly, deserves considerably more attention than that.

    Buried within its proposed amendments to the Tax Procedures Act is a provision that fundamentally changes the relationship between the Kenya Revenue Authority, your business data, and the law enacted specifically to protect it.

    The provision is proposed Section 18A. It would empower the KRA Commissioner to determine whether a person has entered into or carried out a tax avoidance scheme and to issue tax assessments accordingly, using secondary data. The data sources the Bill authorises are broad: withholding tax declarations, employer tax filings, eTIMS transaction records, whistleblower reports, third-party information, KRA audit findings, and any information obtained under other written laws. KRA would have up to five years to issue assessments arising from such determinations.

    This is not a routine tax measure. It is a structural realignment of how the state can access, interpret, and act on your personal and business information, without necessarily asking you first.

    The Finance Bill 2026 matters to every founder running transactions through eTIMS, every fintech operator filing withholding tax records, every digital asset platform with user data sitting in third-party systems, and every business operator whose tax position could be assessed by a regulator who has access to data you have never personally disclosed to KRA.

    Understanding what the Bill proposes, where it conflicts with existing law, and what you should do right now is not optional. It is operational necessity.

    What Section 18A of the Finance Bill 2026 Actually Proposes

    The plain-language version of Section 18A is this: the KRA Commissioner gains the power to form a view that you have engaged in a tax avoidance scheme, and to assess your tax liability on that basis, using data that was collected by other parties for other purposes.

    The secondary data sources the Bill lists are not hypothetical. They are systems already in operation. eTIMS records reflect every transaction your business has processed through the electronic tax invoice management system. Withholding tax declarations carry financial information filed by your counterparties. Employer tax filings show your payroll obligations. Whistleblower reports can come from anyone. Third-party information can originate from financial institutions, other government agencies, or individuals with no direct relationship to your business. KRA audit findings from entirely separate investigations are included.

    The five-year assessment window means that KRA can revisit your tax position for up to five years after identifying a suspected avoidance scheme, using data aggregated across that entire period.

    Two parallel provisions compound the picture. The Bill introduces mandatory annual information returns for virtual asset service providers, requiring them to file detailed user and transaction data with KRA. It also proposes expanded royalty definitions that capture digital payment platforms, card schemes, and switching systems, widening the net of entities under heightened reporting obligations.

    The government frames all of this as modernising Kenya’s tax administration, aligning with global digital enforcement trends, and closing longstanding revenue leakages. That framing is not entirely without foundation. But the mechanism chosen to achieve those objectives raises serious legal questions that no founder operating in Kenya should ignore.

    Data SourceOriginal PurposeProposed New Use Under Section 18A
    eTIMS transaction recordsInvoice compliance and VAT trackingEvidence of tax avoidance schemes
    Withholding tax declarationsThird-party tax deduction reportingSecondary data for income assessments
    Employer tax filingsPAYE and payroll complianceCross-referencing business income positions
    Whistleblower reportsVoluntary information from informantsEvidentiary basis for avoidance determination
    Third-party informationVarious, including financial institutionsSupporting data for assessments
    KRA audit findingsConclusions from separate audit processesCross-use in new avoidance determinations

    Not sure how these provisions affect your specific business? Speak with MNL’s compliance team.

    Finance Bill 2026 Kenya tax documents being reviewed and annotated at a legal desk
    Section 18A of the Finance Bill 2026 proposes to allow KRA to issue tax assessments using secondary data collected by third parties for entirely different purposes.

    Where Finance Bill 2026 Collides with Kenya’s Data Protection Framework

    Kenya’s Data Protection Act 2019 is not aspirational. It is operational, enforceable, and backed by the Office of the Data Protection Commissioner, which has demonstrated a willingness to act. The Act gives effect to Articles 31(c) and 31(d) of the Constitution. It applies to every entity that collects and processes personal data, including financial data, and it applies to government bodies as much as it applies to private ones.

    The proposed KRA framework under Section 18A cuts against four of the DPA’s core principles.

    Purpose Limitation

    Data collected for one purpose cannot be repurposed for another without a fresh lawful basis. When a supplier’s withholding tax data, visible on iTax for payroll compliance purposes, is used to compute an entirely separate tax liability under a suspected avoidance scheme, the purpose for which that data was originally collected has been exceeded. The DPA does not permit this without explicit authority and proportionality.

    Transparency

    Data subjects have the right to know who is accessing their information and why. When whistleblower reports, whose sources a taxpayer may never be permitted to know, form the evidentiary basis of a tax assessment, the transparency requirement has been circumvented. The taxpayer has no visibility into the origin, accuracy, or context of the information driving the assessment against them.

    Automated Processing and Profiling

    The DPA provides that individuals have the right not to be subjected to decisions made solely through automated processing, including profiling. When eTIMS transaction records are fed into KRA’s digital systems to profile business behaviour and generate assessments, this prohibition is directly engaged. KRA has not published the technical architecture of how these assessments will be generated. The absence of that disclosure is itself a transparency problem.

    Data Accuracy

    As EY Associate Director Rachel Njuguna noted in published commentary on the Bill, the risk is concrete: data held by third parties may not accurately reflect a taxpayer’s actual tax position. The proposed framework offers no mechanism for a taxpayer to verify or challenge the accuracy of the source data before an assessment is issued. The burden of disproving an assessment derived from potentially inaccurate data falls on the taxpayer after the fact.

    KRA Proposed PowerConflicting DPA 2019 Protection
    Use eTIMS data to determine tax avoidancePurpose limitation: data must be used only for the purpose collected
    Use whistleblower reports without source disclosureTransparency: data subjects must know who accesses their data and why
    Profile business behaviour through transaction dataRight not to be subject to automated processing with legal effects
    Issue assessments before taxpayer can review source dataRight to challenge inaccurate personal data before legal consequences arise
    Proposed KRA exemption from DPA accuracy obligationsDPA requires all data controllers to maintain accurate, current data

    The Constitutional Dimension

    Kenya’s Constitution is explicit. Article 31 guarantees every person the right to privacy, including the right not to have information relating to their family or private affairs unnecessarily required or revealed. Any law that limits this right must satisfy Article 24, which requires that the limitation be reasonable and justifiable in an open and democratic society, and that it be proportionate to the objective being pursued.

    Civil society organisations, including Amnesty International Kenya and ARTICLE 19 Eastern Africa, have assessed the proposed expansion of KRA’s data powers directly. Their conclusion is unequivocal: the provision does not meet the Article 24 threshold. The limitation goes beyond what is necessary to achieve the stated objective of closing tax revenue leakages. Less intrusive enforcement mechanisms already exist and are in active use.

    The due process concern is compounded by the proposed exemption of KRA from certain DPA accountability obligations. If the Bill is enacted as drafted, KRA would face reduced obligations to ensure that the data it uses is accurate, to maintain clear data retention policies, and to give taxpayers meaningful visibility into how their information is being used. For a framework that will determine tax liabilities, with direct legal and financial consequences for individuals and businesses, that is a significant gap.

    Article 47, the right to fair administrative action, reinforces the concern. Where an administrative decision is likely to adversely affect a person, that person is entitled to written reasons and an opportunity to be heard. An assessment issued on the basis of third-party secondary data, without prior disclosure of that data to the taxpayer, raises serious questions about compliance with Article 47 obligations.

    This Pattern Is Not New

    Finance Bill 2026 is not the first time this boundary has been tested, and understanding the pattern matters for how you position your business going forward.

    Finance Bill 2025 contained a provision seeking to repeal Section 59A(1B) of the Tax Procedures Act, a statutory safeguard that then prohibited KRA from compelling taxpayers to disclose personal data or trade secrets obtained during business operations. That proposal drew fierce opposition from the Law Society of Kenya, KPMG East Africa, and Ernst and Young. KRA’s Commissioner General subsequently committed, before the Departmental Committee on Finance and Economic Planning, to work with the Office of the Data Protection Commissioner on a Data Minimisation Strategy under the 9th Corporate Plan.

    Finance Bill 2026 returns to the same contested territory. The mechanism is different but the practical effect is the same: expanding KRA’s reach to data that the existing legal framework was not designed to accommodate without additional safeguards.

    The policy direction is now clear across successive Finance Bills. Kenya is moving toward a data-driven tax enforcement model. Whether Parliament enacts or moderates these specific provisions, the trajectory will not reverse. Businesses need to be positioned for a compliance environment where the state has broader access to financial data than it has had at any previous point, where assessments can be generated from aggregated secondary sources, and where the burden of proving inaccuracy may rest with the taxpayer.

    Preparation now costs far less than litigation later. That is not a theoretical observation. It is the consistent finding of every business that has waited for enforcement pressure before addressing its compliance posture.

    Five Things Founders and Business Operators Should Do Right Now

    This is about operational readiness, not legal panic. The Bill has not passed. You have time to act intelligently. Here is where to start.

    1. Audit Your Digital Data Footprint

    Every transaction processed through eTIMS, every withholding tax record filed against your PIN, and every employer filing associated with your payroll is already visible within KRA’s digital systems. Under the proposed framework, this data can be aggregated, cross-referenced, and used to assess your tax position without a prior audit flag. Accuracy in your digital records is no longer merely good practice. It is your first line of defence. Reconcile your eTIMS records against your own books now, before any assessment process begins.

    2. Know Your Rights as a Data Subject

    Even before these amendments are enacted, the Data Protection Act 2019 gives you rights that apply today. You can request to know what personal data KRA holds on you. You can challenge inaccuracies in that data. You have the right to be informed about automated processing that produces legal effects. These rights exist under current law, and exercising them proactively creates a documented record that is valuable if an assessment dispute arises. Understand your Data Protection Act 2019 obligations and the corresponding rights they give you.

    3. Engage the Public Participation Process

    Finance Bill 2026 is at the public participation stage before the National Assembly. This is a formal legal opportunity to submit memoranda, appear before the committee, or support industry associations presenting evidence-based objections. Bowmans and other firms have already made public submissions on specific provisions. The window is open. Founders with direct knowledge of how data-driven tax assessments would affect their operating models have information the committee needs and does not yet have from affected parties at scale.

    4. Assess Your Obligations If You Operate in Fintech or Digital Assets

    Virtual asset service providers and digital payment platforms face the most immediate and specific new obligations under the Bill. If your business falls within those categories, the question of what data you will be required to file, when, and under what governance framework requires legal advice now, before enactment. The fintech reporting compliance Kenya landscape is changing materially with this Bill, and the obligations are not minor.

    5. Document Your Internal Data Governance

    If your data is going to be used in an assessment against you, the best protection is records that speak for themselves. Clear internal policies on data retention, transaction documentation, and reconciliation processes that can withstand external scrutiny are not just compliance infrastructure. They are your evidentiary foundation in any dispute. Building strong corporate data governance in Kenya now converts a future risk into a managed position.

    Not sure how Finance Bill 2026 affects your specific business model? Our Team can walk you through the risk exposure and what documentation you need in place before this Bill passes. Book a compliance review with MNL.

    The Window to Act Is Open

    Finance Bill 2026 does not exist in a regulatory vacuum. Kenya has a Data Protection Act. It has a functioning Office of the Data Protection Commissioner. It has a Constitution with an enforceable bill of rights. None of these are suspended by a Finance Bill.

    The legal question Parliament must answer before enacting Section 18A is not whether tax enforcement matters. It plainly does. The question is whether this particular mechanism, with its current absence of taxpayer safeguards, data accuracy obligations, and transparency requirements, is the proportionate and lawful means of achieving that objective.

    For businesses, the practical question is narrower but no less urgent: are you operationally prepared for a tax environment where secondary data can drive assessments, where the burden of proving inaccuracy may fall on you, and where the data generating those assessments may be held by parties you have never directly dealt with?

    The Bill is before the National Assembly. The public participation window is open. Your records are either accurate and documented or they are not. Your data rights are either understood and exercised or they are not. The cost of getting ahead of this is low. The cost of responding to an assessment after the fact is not.

    Ready to understand exactly how Finance Bill 2026 affects your business?
    MNL Advocates LLP advises clients across fintech, technology, and commercial law on regulatory compliance, data protection, and tax matters in Kenya and across East Africa.
    Initiate a Confidential Consultation with MNL.

    Frequently Asked Questions: Finance Bill 2026 and KRA Data Powers

    What does Section 18A of the Finance Bill 2026 allow KRA to do?

    Section 18A proposes to empower the Kenya Revenue Authority Commissioner to determine whether a person has entered into or carried out a tax avoidance scheme and to issue tax assessments accordingly using secondary data. The authorised sources include withholding tax declarations, employer tax filings, eTIMS transaction records, whistleblower reports, third-party information, KRA audit findings, and information obtained under other written laws. KRA would have up to five years to issue assessments arising from such

  • Mauritius – An Emerging Hub for Fintech & Payment Solutions in Africa

    Mauritius – An Emerging Hub for Fintech & Payment Solutions in Africa

    Mauritius – An Emerging Hub for Fintech & Payment Solutions in Africa

    In the past decade, Mauritius has emerged as a strategic location for a variety of financial services in Africa. Under the guidance of the Mauritius Financial Services Commission (FSC), a robust framework now exists for the regulation of derivatives activities, payment & banking services, as well as digital asset / virtual currency projects. 

    Payment Services for Africa & The Globe

    Starting off with payment services, Mauritius offers two distinct licenses: Payment Intermediary Services (PIS) and Payment Service Provider (PSP). There are major differences between these licenses which are worth delving into greater detail. 

    The major distinction between the PIS and PSP license is that the former is overseen by the Mauritius FSC while the Bank of Mauritius issues all PSP licenses. From our professional experience, the PIS license is more attractive due to lower capital requirements (2,000,000 MUR), a speedier license approval period as well as lower substance requirements. Furthermore, the PIS license is a better fit for cross-border payment services with the PSP license being issued primarily for local business in Mauritius itself. Finally, the Payment Intermediary Services license focuses primarily on card issuance services. Experience has shown that higher demand exists for card and mobile payment services throughout Africa, making the PIS license a better fit for the majority of new payment projects.  

    Derivatives & Virtual Currency

    Moving on to exchange traded products, Mauritius has two distinct regulatory paths for brokers and digital asset providers / crypto exchanges. On the brokerage side, the FSC has a unique license class for brokerage services, known as an Investment Dealer. This license allows one to offer brokerage services in derivatives, stocks, and futures which can be used to target a global audience. An additional benefit of the Investment Dealer license is the underwriting permission. By upgrading the Investment Dealer license to this permission set, licensed brokerage firms in Mauritius will have the ability to initiate stock listings on the Mauritius public stock exchange. 

    In addition to derivatives regulation, Mauritius also for the establishment of fully regulated digital asset firms. VAITOS 2021, which is the regulatory framework for crypto licensing in Mauritius, sets the standard for Virtual Asset Service Provider (VASP) regulation. Licensed activities include: exchange permissions, wallet services, custodian of tokens, and exchange services. 

    Investment Banking Activities

    Finally, the Mauritius FSC also provides a clear pathway for the establishment of an Investment Banking license. A key advantage is flexibility as a variety of financial activities are permitted under this license. Examples of permitted activities include: merger & acquisition advisory, asset management, securities dealing, the underwriting of securities, as well as corporate finance. It is important to highlight that receiving deposits and other types of banking activities do require separate authorisation from the Bank of Mauritius, making a clear distinction between investment and commercial banking activities. 

    In addition to this level of flexibility, Mauritius offers two major incentives to firms looking to establish a presence on the island. First, Mauritius currently has 46 Double Tax Agreements with a variety of countries around the world, examples include China, South Africa, UK and France. Additionally, any new investment bank will enjoy a 5 year tax holiday from the standard 15% corporate tax rate. 

    Discover the Benefits of Mauritius Regulation Today!

    As interest in mobile payment services and digital assets continues to grow throughout Africa and the world, Mauritius will remain the ideal jurisdiction for the quick and efficient regulation of these emerging financial services. We hope this brief overview was useful in providing a basic introduction to Mauritius.

    For many businesses, it strikes the right balance between innovation and compliance.

    At MNL Advocates LLP, we work closely with fintech companies, financial institutions, and investors to navigate complex regulatory landscapes across Africa and offshore jurisdictions such as Mauritius.

    Our support includes:

    • Advising on the most suitable licensing structures (PIS, PSP, VASP, Investment Dealer, Investment Banking)
    • Managing end-to-end license applications and regulatory engagement
    • Structuring cross-border operations and corporate entities
    • Drafting compliance frameworks and internal policies
    • Providing ongoing legal and regulatory support
    • Acquisition of a fully licensed Investment Dealer or VASP firm.

    Whether you are launching a fintech startup or expanding an existing operation, our team is well-positioned to guide you through every stage of the process.

    Have questions or exploring Mauritius as your next hub? Get in touch with MNL ADVOCATES LLP to start the conversation.

  • Guide to Licensing Payments in Kenya: A Strategic Approach

    Guide to Licensing Payments in Kenya: A Strategic Approach

    PSP and e-money pathways, VASP developments, and compliance as a commercial asset for fintechs operating in Kenya.

    Kenya’s payments market is often described in the language of speed: faster checkout, instant transfers, real-time settlement, embedded finance. That narrative is accurate but incomplete. Payments innovation at scale is not only a product story. It is a regulatory perimeter story, and increasingly a governance and resilience story.

    When a business operates in payments in Kenya, whether through a gateway, a digital wallet, merchant acquiring, or a platform layered onto mobile money rails, the question that matters is not simply whether the product works. It is whether the product is operating inside a licensing framework that regulators, counterparties, and sophisticated customers can recognise as safe.

    Key insight: Licensing is not merely an approval step. It is an operating standard testing capital, governance, AML/CFT readiness, cybersecurity, reporting capability, and data governance.

    Contents

    1. The core shift: licensing as operational readiness
    2. Who regulates payment services in Kenya
    3. The payments licensing perimeter
    4. PSP licensing pathways: why “PSP” is not one licence
    5. Virtual assets: what the VASP Act signals
    6. When payments drifts into banking-style regulation
    7. Compliance as a commercial asset
    8. Timelines and capital: planning realistically
    9. FAQ

    1. The Core Shift: Licensing as Operational Readiness

    Early-stage teams sometimes treat licensing as a binary hurdle: licensed or not licensed. In practice, regulators treat licensing as a continuous assurance framework. It requires firms to demonstrate, before launch and throughout operations, that they can manage financial risk, conduct and consumer risk, financial crime risk, technology and operational risk, and data governance.

    This changes how founders should plan. If licensing is treated as a late-stage filing exercise, it often collides with reality: incomplete governance, unclear control ownership, weak documentation, and vendor arrangements that do not match the regulatory story the firm wants to tell.

    2. Who Regulates Payment Services in Kenya

    For most payment service providers and payment systems, the Central Bank of Kenya (CBK) is the anchor regulator under the National Payment System framework. CBK’s focus is pragmatic: safeguarding the integrity and stability of the payment ecosystem and protecting users.

    Depending on the business model, other authorities may also be relevant:

    • Capital Markets Authority (CMA) where virtual assets or investment-adjacent features appear.
    • Communications Authority where telecom rails or authorisations are integral to the model.
    • Financial Reporting Centre (FRC) for AML/CFT reporting obligations.
    • Office of the Data Protection Commissioner (ODPC) for data protection compliance.
    • Kenya Revenue Authority (KRA) for tax compliance.

    3. The Payments Licensing Perimeter: Substance Over Labels

    The fastest way to understand licensing is to describe the product functionally rather than in marketing terms. Regulators are generally less interested in whether a product is called a “platform” or a “technology provider,” and more interested in what it controls:

    • Transaction initiation and processing.
    • Issuance of stored value.
    • Operation of a payment instrument or payment system.
    • Control over settlement flows.
    • The integrity of communications to users.

    In practical terms, licensing outcomes often turn on where the business sits in the value chain: whether it is processing payments, operating payment rails, issuing e-money, or touching customer funds even briefly.

    4. PSP Licensing Pathways: Why “PSP” Is Not One Licence

    “PSP licence” is commonly used as shorthand, but in practice there are distinct categories that reflect different risk profiles, particularly the distinction between facilitating payments and issuing stored value.

    Electronic Retail Payments and Transfer Services (Without E-Money)

    This category generally captures providers facilitating electronic retail payment transactions such as gateways, acquiring and processing, and bill payments, without issuing stored value.

    Small E-Money Issuer (SEMI)

    SEMI structures recognise that some wallet products are low-value or limited in scope. While thresholds may differ, the underlying supervisory expectations remain meaningful: governance, AML/CFT controls, cybersecurity posture, and reporting capability must be credible.

    E-Money Issuer

    Where a platform issues, stores, and redeems e-money, particularly where it is usable with third parties, the regulatory intensity typically rises. At this level, safeguarding structures, reconciliations, consumer risk, and operational resilience become central.

    Payment Instruments and Payment Systems

    Where a business owns or operates payment instruments or systems, including switching or settlement-adjacent infrastructure, the authorisation posture can shift again, particularly where scale raises systemic considerations.

    5. Virtual Assets: What the VASP Act Signals for Kenya Fintechs

    Kenya’s Virtual Asset Service Providers Act, 2025 signals a formal shift toward licensing and supervision of digital asset activity. While implementing regulations and guidelines are awaited, the strategic implication for product teams is immediate: classify activities honestly (custody, exchange, issuance, advisory) and build for licensing readiness in governance, AML/CFT maturity, cybersecurity controls, and defensible disclosures.

    6. When Payments Drifts Into Banking-Style Regulation

    A common strategic risk is designing a payments product that quietly begins to resemble deposit-taking or bank-like services. Where a model involves deposit-like accounts, savings behaviour, or lending structures, the licensing framework can shift into a materially stricter regime under the Banking Act.

    Product design should therefore be treated as regulatory design, particularly where the roadmap includes credit, savings, or account-like features.

    7. Compliance as a Commercial Asset for Kenya Fintechs

    For growth-stage fintechs, licensing and compliance are often viewed as cost centres. In reality, they are frequently deal accelerators. Sophisticated counterparties increasingly ask for evidence: who owns AML/CFT controls, what cybersecurity standards are implemented, how personal data is handled, what incident response looks like, and whether vendor relationships allocate responsibilities clearly.

    Firms that can answer these questions with coherent documentation, including governance papers, policies, logs, and enforceable contracts, move faster in negotiations and inspire confidence in partners and investors.

    8. Timelines and Capital: Planning Realistically

    Licensing is a project, not a form. A realistic plan allows time for pre-application engagement, application review, regulator queries, and final issuance steps. Depending on the model and readiness, timelines can extend over several months and, in some cases, closer to a year.

    Minimum capital requirements vary by category. Examples commonly referenced for certain PSP categories include:

    • Small E-Money Issuer (SEMI): KES 1,000,000
    • Electronic retail payments services: KES 5,000,000
    • E-Money Issuer: KES 20,000,000
    • Designated payment instrument issuer: KES 50,000,000

    Capital, however, is rarely the only determinant of speed. Governance and operational controls are often what determine momentum through the licensing process.

    MN Legal supports clients across the lifecycle of payment and digital finance businesses, from early model structuring to licensing submissions and ongoing compliance posture. This includes mapping transaction flows to the right authorisation pathway, preparing governance and compliance documentation, aligning AML/CFT and operational resilience expectations, advising on data protection governance, and structuring partner and vendor contracts so the operating model matches the regulatory position.

    Make an enquiry  |  Explore Practice Areas

    Frequently Asked Questions

    What licence does a payment service provider need in Kenya?

    It depends on the model. The CBK regulates most PSP activity under the National Payment System framework. The right category depends on whether the business is processing payments, issuing e-money, operating payment instruments, or touching settlement flows. There is no single “PSP licence.”

    How long does payment licensing take in Kenya?

    Realistically, several months from pre-application engagement to issuance, and in some cases closer to a year. Governance and operational controls readiness often determines pace more than capital alone.

    What does the VASP Act mean for digital asset businesses in Kenya?

    The Virtual Asset Service Providers Act, 2025 introduces a formal licensing and supervision framework for digital asset activity. Businesses should classify their activities honestly and begin building for licensing readiness now, ahead of implementing regulations.

    Can a payments product drift into banking regulation?

    Yes. Where a model begins to resemble deposit-taking, savings, or lending, the applicable framework can shift toward the Banking Act, which carries significantly stricter requirements. Product design should be treated as regulatory design from the outset.

    Why does licensing matter commercially, not just regulatorily?

    Sophisticated partners, investors, and enterprise customers increasingly ask for evidence of governance, AML/CFT controls, cybersecurity posture, and data protection compliance. Firms with coherent documentation move faster in commercial negotiations and due diligence processes.

    How can MN Legal help with Kenya payments licensing?

    MN Legal advises on model structuring, licensing pathway selection, governance and compliance documentation, AML/CFT readiness, data protection governance, and vendor and partner contracting for payment and digital finance businesses operating in Kenya.


    Disclaimer: This article is for general information only and does not constitute legal advice. Licensing requirements vary by jurisdiction and specific facts. For advice on your specific model, contact MN Legal.

  • How Capital Markets Licensing Affects Legal Tech Providing Investment, Crowdfunding or Securities Solutions

    How Capital Markets Licensing Affects Legal Tech Providing Investment, Crowdfunding or Securities Solutions

    The most commercially successful legal-tech products in capital markets are often the least dramatic: tools that help licensed
    intermediaries keep clean records, onboard investors efficiently, deliver disclosures with audit trails, and demonstrate compliance
    during due diligence.

    Yet licensing questions arise precisely because these products sit close to the regulatory frontier. A platform may be built as
    “workflow software” and still be treated as a regulated service if, in substance, it gives investment recommendations, arranges
    transactions, holds client money, or functions as part of the public offering machinery.

    Abstract capital markets licensing and legal-tech compliance graphic (no logos)
    Licensing risk is rarely about labels. Regulators look at function, control, and investor impact.

    Executive summary: Capital markets regulators tend to apply a functional approach. If your platform performs, controls,
    or materially influences regulated activity, licensing or a licensed partner model may be required, regardless of how the product is marketed.

    The licensing perimeter: the standard regulators apply

    Across most capital markets regimes, licensing is not triggered by a company’s branding (“we are a technology company”) but by what
    the company does. This is sometimes described as a substance-over-form or functional approach.

    In practical terms, the perimeter tends to tighten around four activities:
    (i) giving investment advice or making personalised recommendations,
    (ii) arranging, placing, routing, or executing transactions,
    (iii) handling client money, securities, or custody-like flows, and
    (iv) facilitating public offering communications in a way that creates mis-selling or disclosure risk.

    Legal-tech tools can sit safely outside the perimeter when they operate as internal compliance infrastructure for a licensed intermediary
    and remain subject to clear boundaries: the tool supports, records, and evidences; the licensed entity decides, approves, and executes.

    Where legal-tech products typically trigger perimeter concerns

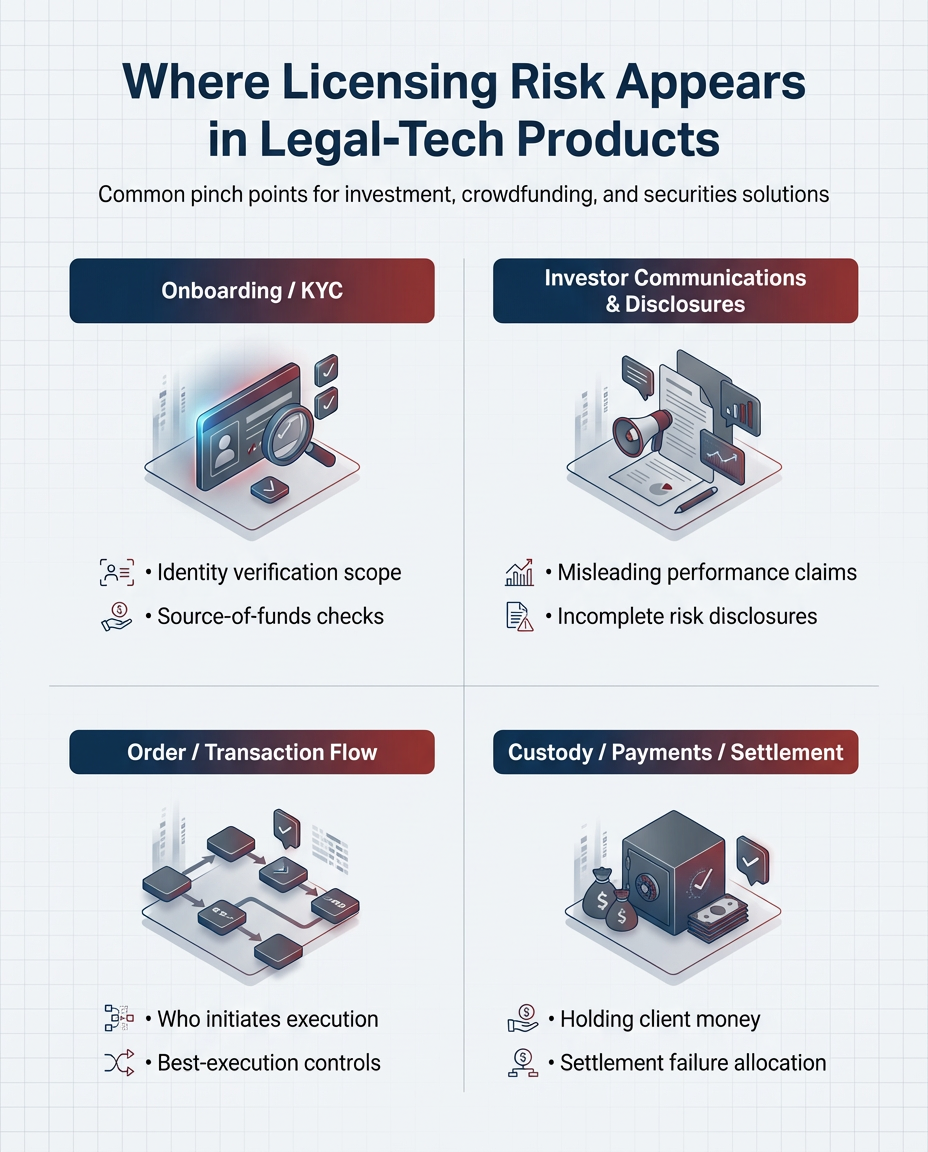
    Licensing risk most often appears not in a single feature, but in the way features combine into a workflow. Products designed for
    investor onboarding, digital disclosures, and transactional workflow can become “front office” infrastructure very quickly.

    Where licensing risk appears in legal-tech products (onboarding, disclosures, transaction flow, custody)

    Onboarding, disclosures, order flow, and custody-adjacent design are the most common perimeter pressure points.

    Investor onboarding and eligibility

    KYC and onboarding tooling is generally defensible when it remains a controlled workflow with clear oversight. Risk escalates when
    the platform begins to make final determinations (who may invest, what products are suitable) without the licensed intermediary’s
    meaningful review, or where the “profiling” output becomes a de facto recommendation.

    Digital disclosures and investor communications

    Digital disclosure tools are often low-risk, and highly valuable, when they solve the evidence problem: document versioning,
    distribution logs, acknowledgements, and audit trails. Concerns arise where communications drift into promotion of an offer to the
    public without adequate controls, or where disclosures are delivered without traceable evidence of what the investor received and when.

    Order and transaction workflows

    Interfaces that display information are one thing; workflows that route orders, “match” investors to opportunities, or control
    execution logic may look like arranging or execution activity depending on the jurisdiction and the facts.

    Custody, payments, and settlement-adjacent flows

    Products that touch client funds directly or through accounts the platform controls require particular care. Even where a third-party
    payment provider is involved, the question regulators ask is who controls the flow and who bears responsibility for safekeeping.

    A practical perimeter test for founders and buyers

    The most efficient way to avoid late-stage licensing surprises is to run an early perimeter test and write down the conclusion.
    Think of it as a short internal legal memo that you can update at every major release.

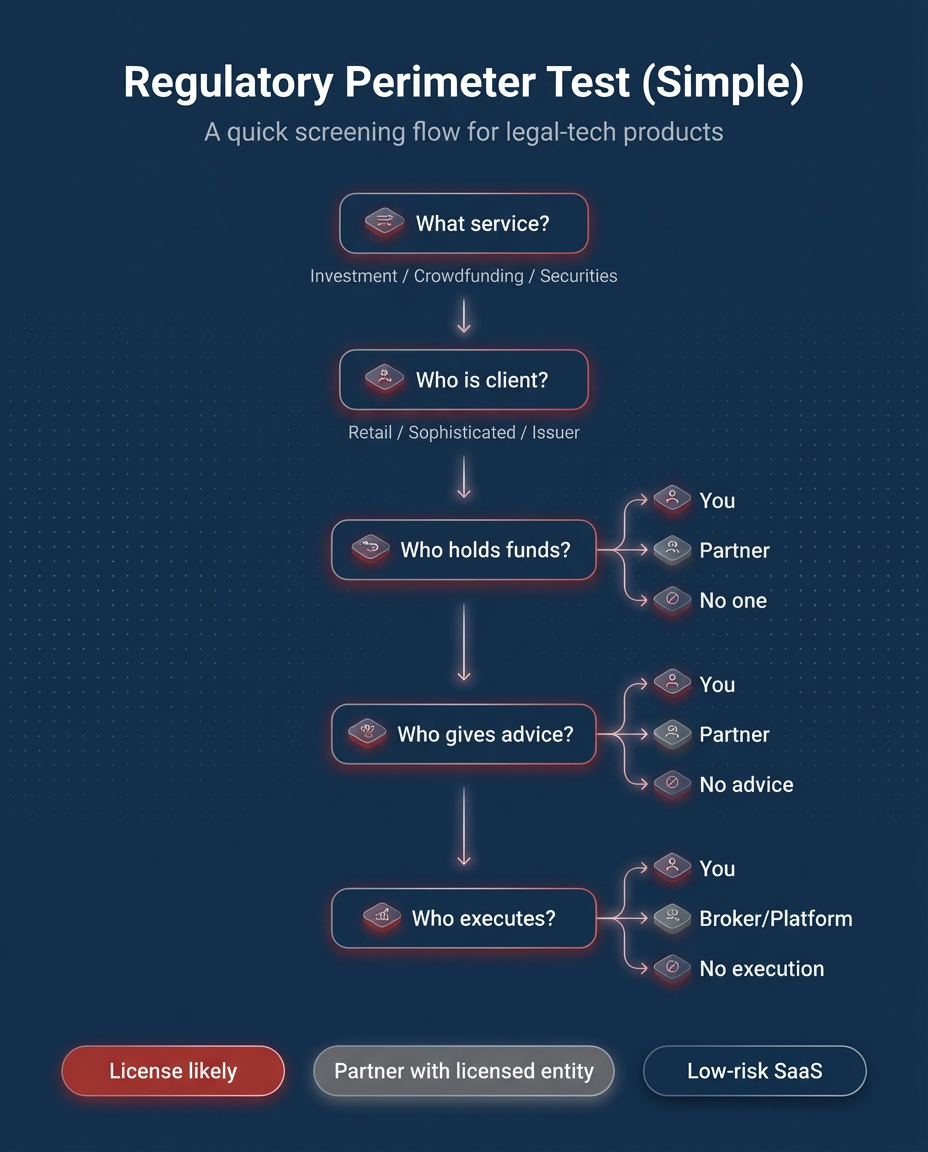
    Regulatory perimeter test flowchart for legal-tech serving capital markets
    A simple test helps teams classify risk before product scope drifts.

    The test is deliberately plain. It asks: what service is the product enabling; who is the client; who touches money; who influences
    decisions; who executes; and who controls the communications. If the honest answers point toward advice, arranging/execution, custody-like
    flows, or public offer facilitation, then the product should be structured around a licensed entity either by obtaining the relevant
    permissions or by partnering with a licensed intermediary and allocating responsibilities clearly.

    Designing for compliance: standards that travel across jurisdictions

    Legal-tech teams operating internationally need principles that work across regimes even where definitions differ. The following
    standards tend to be robust:

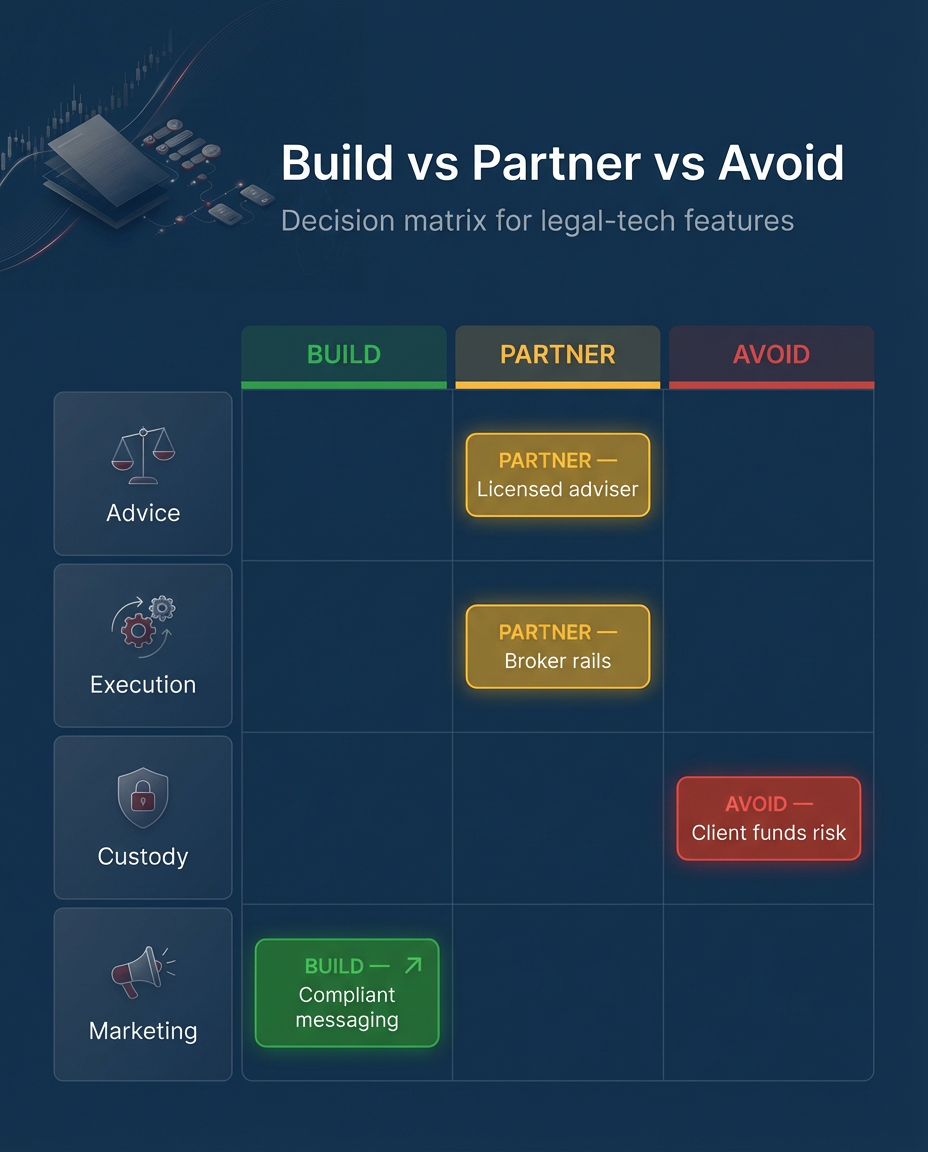
    Build vs partner vs avoid matrix for licensing-sensitive product features
    A product decision matrix keeps commercial teams, engineers, and compliance aligned.

    First, keep regulated functions with the licensed entity where required. Second, build systems that generate evidence: approvals,
    versioning, acknowledgements, exception handling, and user action logs. Third, ensure that governance is not merely documented,
    but operational meaning there are named owners, review points, and the ability to demonstrate what happened in a specific investor journey.

    The strategic benefit is commercial as much as legal. Strong evidence and clearly bounded operating models reduce friction in procurement,
    accelerate partner onboarding, and make regulatory discussions more orderly.

    A realistic scenario: when “crowdfunding software” becomes a regulated service

    Consider a platform built initially to support issuers with document workflows: issuer onboarding, disclosure templates, and investor
    acknowledgements. The tool performs well and demand grows. Then the roadmap adds convenience features: investor “matching,” automated
    eligibility approval, and in-platform collection of funds “to simplify settlement.”

    Each feature looks incremental. Collectively, the platform may now resemble the machinery of a public offer and transaction facilitation.
    At that point, the perimeter question becomes unavoidable: is the platform merely enabling a licensed intermediary, or is it effectively
    arranging participation, influencing investment decisions, and controlling flows that look custody-adjacent?

    The fix is usually not a full rebuild. It is a structural decision: allocate regulated steps to a licensed partner (or obtain the
    necessary permissions), revise workflows to ensure meaningful oversight, and strengthen disclosures and records so the investor journey
    is defensible.

    Governance and documentation: what sophisticated partners will ask for

    Intermediaries, institutional partners, and sophisticated clients increasingly require evidence of regulatory thinking. A premium posture
    is to maintain a living file that includes: a perimeter memo, a feature risk register, an operating model diagram, vendor allocations,
    and a compliance evidence map (what logs exist, who reviews them, and how exceptions are handled).

    This is where legal-tech has an advantage. Unlike traditional paper processes, well-designed systems can produce reliable logs and
    demonstrate accountability. The goal is not to generate paperwork; it is to make compliance auditable.

    How MN Legal helps

    Perimeter advice, partner models, and defensible product workflows

    MN Legal advises legal-tech founders and capital markets intermediaries on regulatory perimeter mapping, licensing and partnering
    structures, disclosure and onboarding workflow design, and the contractual allocation of responsibilities between platforms and
    licensed entities. Where appropriate, we also support incident readiness and records strategy so your compliance posture is
    evidenced not assumed.

    Make an enquiry

    External reference points that inform global standards include
    IOSCO (securities regulation principles),
    FATF (AML/KYC expectations),
    and market regulators such as
    ESMA and the
    FCA.

    FAQ

    Does every investment or crowdfunding tool require licensing?

    No. Many tools remain outside the perimeter when they are genuinely internal compliance or recordkeeping infrastructure for a licensed
    intermediary. Risk depends on function and control particularly advice, arranging/execution, custody-like flows, and public communications.

    What features most often create licensing pressure?

    Personalised recommendations, investor matching/placement functions, order routing or execution logic, custody-adjacent payment flows,
    and public offer communications without robust controls.

    How should international legal-tech teams manage multi-jurisdiction uncertainty?

    Start with consistent standards: a perimeter memo, a feature risk register, a partner model where regulated steps are performed by
    licensed entities, and strong evidence (audit trails, disclosure versioning, acknowledgements, exception workflows).


    Disclaimer: This article is general information and not legal advice. Licensing requirements vary by jurisdiction and facts. For advice on your specific model, contact MN Legal.